Men Who Are Genuinely Happy in Retirement Avoid These 8 Common Traps

Most men spend twenty years planning the money and about twenty minutes planning the life. Then the second Monday arrives.
The first Monday feels like a holiday. You sleep in, you finish your coffee slowly, and nobody calls. The second Monday is when the quiet starts to feel different.
Here is what the research shows about the retirement mistakes men make. Nearly half of retirees leave work earlier than they planned. Three out of four of them give a reason they never picked: a health problem, a layoff, a company that reorganized around them. Most men expect to stop at 65. The typical man actually stops at 62.
That gap matters. It means retirement usually shows up on a schedule you did not set, in a shape you did not design.
This article walks through eight traps and one fix for each. The list moves from money to purpose to people to health, because that is the order most men get wrong. Every section ends with something you can start this week.
Close to half of retirees leave work sooner than they planned.
Three in four of those had no say in the timing.
1. Your Retirement Date May Not Be Yours to Pick
You probably have a year in your head. Maybe a month. Most men do.
The problem is that the date often picks you first. Close to half of retirees stop working sooner than they planned, and most of them had no say in it. The biggest single reason is a health problem or a disability. The second is a change at the company: a closure, a merger, a reorganization that quietly removes your role.
Only a small share of men get the slow wind down they pictured. Most just stop one day.
So the plan built around age 65 has to survive age 62. If it cannot, it is not a plan. It is a hope.
What to do this week: run your budget as if you stopped working three years earlier than you intend to. Two questions matter most. Does the money still last? And how would you pay for health coverage in the years before Medicare starts at 65? If your employer offers severance terms or retiree medical benefits, find out now what they actually cover. People who ask that question after the layoff have no leverage left.
If the date can move, so can every decision hanging off it. Starting with the biggest one.
2. Why Filing for Social Security at 62 Can Cost You for Life
Age 62 is the first year you can file. It is also the most popular year for men to file. Fewer than one man in ten waits until 70.
That choice is permanent. Whatever you lock in at 62 is roughly what you get every month for the rest of your life, adjusted for inflation but never re-decided.
Here is the size of the gap. Filing at your full retirement age gives you your full benefit. Filing at 62 cuts it by about 25% to 30%. Waiting past full retirement age adds roughly 8% a year until you turn 70. Stretched across the whole range, a man who waits until 70 can collect close to double the monthly check of a man who filed at 62 on the same work record.
Bar length shows the size of your monthly check relative to waiting until 70.
Every year you wait past your full retirement age adds roughly 8%, and it never goes back down. Fewer than one man in ten waits until 70.
Research on lifetime income says most workers in their fifties and early sixties would collect more money overall by waiting until 70. Almost none of them do.
When filing early is the right call
This is not a rule for everyone, and anyone who tells you it is has not looked at your situation. Filing early makes sense if:
- You have a serious health condition and a shorter life expectancy
- You have no savings or income to live on between now and full retirement age
- You need the money to avoid taking on debt
- Your spouse has a small work record of her own and you are the lower earner of the two
That last point cuts both ways. If you are the higher earner, your filing age also sets the survivor benefit your wife may live on for years after you are gone. Waiting protects her, not just you.
What to do this week: create an account at ssa.gov and pull up your own estimate at 62, at full retirement age, and at 70. Look at the real numbers instead of the general advice. Then ask a simple question: could you cover your expenses from savings for a few years in exchange for a permanently larger check? That trade is called a bridge, and for a man in decent health it is often the single most valuable decision on this list.
3. What Medicare Will Not Pay For
More than half of men approaching retirement believe Medicare covers all their health costs. It does not come close.
A single 65 year old man retiring today should expect to spend well over $180,000 on health care across the rest of his life, even with Medicare. For a couple, the number roughly doubles. And that figure leaves out the biggest expense of all.
Long term care is not covered. Not nursing homes, not assisted living, not a home aide who helps you bathe. Someone turning 65 has close to a 70% chance of needing some form of it. That cost sits entirely outside the number above.
Here is what Medicare actually leaves on your side of the line:
- Hospital stays, most of the bill
- Doctor visits and outpatient care
- Lab work and preventive screening
- Prescriptions, partly, through Part D
- Monthly premiums, taken from your check
- Deductibles and coinsurance
- Dental, vision and hearing aids
- Long term care, entirely
More than half of men approaching retirement believe Medicare covers everything. The single biggest expense, long term care, sits completely outside it.
The squeeze is real and it gets worse each year. Your Social Security raise goes up by a small percentage. Your Medicare premium goes up by a larger one. The difference comes out of your grocery money.
Fewer than half of men have ever sat down and calculated any of this.
What to do this week: if you are still working and you have a high deductible health plan, put money in a health savings account. It is the only account that goes in tax free, grows tax free, and comes out tax free for medical costs, and it follows you into retirement. If you are already retired, price a Medigap policy and look at long term care coverage as two separate problems. Do not assume Medicare handles either one.
Which raises the next question: how much can your savings actually give you each year?
4. How to Spend Your Savings Without Fear or Regret
You have heard the 4% rule. Take 4% of your savings the first year, raise it with inflation, and the money lasts thirty years.
It started as one researcher’s finding decades ago. It became treated like a law of physics. It is neither.
Current research puts the safe starting figure a little below 4% for a man who wants the exact same income every single year, no matter what the market does.
But here is the part almost nobody mentions. If you are willing to flex your spending, trimming a little after a bad year and taking more after a good one, that same research says you can safely start well above 5%.
Read that again. The rigid plan gives you less money, not more. Flexibility is what pays.
There are two ways men get this wrong, and they look like opposites:
Overspending early. About four in ten retirees say their expenses turned out higher than they expected. The first years of retirement are the expensive ones. You have time, energy, and a list of things you waited forty years to do.
Underspending out of fear. Roughly half of retirees admit they spend less than they could because they are scared of running out. This is the quieter failure. Nobody notices it. It shows up as trips not taken and a smaller life, while the balance sits there doing nothing for anybody.
What to do this week: set guardrails instead of a fixed percentage. Pick a starting withdrawal. Then write down two rules in advance: if the portfolio drops a set amount, you cut spending by a set amount. If it climbs, you give yourself a raise. Deciding this while you are calm beats deciding it during a market drop.
That is the money handled. Now the part almost nobody plans.
5. How to Retire To Something, Not Just Away From a Job
By week three the garage is organized. The gutters are clean. The list you built over twenty years is done, and it took less than a month.
This is where a lot of men get quiet.
You planned the exit in detail. You left the arrival blank. And work was doing more for you than you knew. It gave you a reason to get up, people who expected you, and a clear answer to the question men get asked within four minutes of meeting anyone.
Purpose is not a soft idea. Among adults over 50, those with the strongest sense of purpose have a meaningfully lower risk of dying over the following years than those with the weakest.
Purpose also tracks with slower memory decline and lower risk of dementia. It tends to fall as men age, and leaving the workplace is one of the main reasons why. Work supplies direction by default. Nothing replaces it automatically.
The mistake right after this one: swearing off work entirely
About three quarters of workers say they plan to work for pay in retirement. Only about a third of retirees actually do.
That gap is worth pausing on, because the research on men specifically is clear. Men who keep working, full time or part time, report better emotional wellbeing than men who stop completely. This holds even when the job is nothing special. Some work after retirement also lowers the odds of loneliness in men. Stopping raises them.
This is not a call to grind until you drop. It is a call to stop treating any work at all as a failure. Eight hours a week of consulting counts. So does seasonal work, a board seat, teaching your trade at a community college, or a paid role at a nonprofit you care about.
One warning. Most men picture a gradual wind down and then stop all at once instead. A phased exit has to be negotiated while you still have something to trade. Once you resign, you have nothing to negotiate with.
What to do this week: name three things that will want your time on a Tuesday morning. Not hobbies. Commitments, with other people expecting you to show up. A standing volunteer shift, a class you teach, a project with a deadline. A hobby you can skip is not a structure.
Work gives men one more thing that is even harder to replace.
6. How to Keep Your Friends After You Hand In the Badge
Think about the men you talked to most last month. Now take away everyone you met through work.
For a lot of men, that list gets very short.
Most male friendships are built on shared logistics. You see the same guys because you are in the same building five days a week. Nobody has to organize anything. When the job ends, the whole arrangement ends with it, and almost no one notices until a few months have passed.
The numbers on this are worse than most men assume. Among American men, the share with six or more close friends has dropped by half over the past three decades.
The share with no close friends at all has risen fivefold. Among adults over 45, roughly four in ten now say they feel lonely, and men now report higher rates than women. That is a reversal from where things stood a few years ago.
Retirement is one of the events that triggers it. Lonely adults spend well over an hour more alone each day than everyone else, and they are less likely to stay in touch with former colleagues.
That last detail matters, because it points at the fix. The difference is not luck. It is maintenance.
One of the longest running studies of adult life has followed the same men for more than eighty years. Its clearest finding is that the quality of your relationships predicts your health and happiness better than money, status, or intelligence. The researchers call the upkeep social fitness. Relationships need work the way muscles do. Skip it for a year and you lose ground.
What to do this week: set up one recurring, scheduled, in person commitment with other men. A Thursday breakfast. A Saturday round. A workshop, a league, a veterans group, a church committee. It has to be recurring, because spontaneous plans die quietly. Nobody organizes the reunion twice.
There is one relationship you do not lose in retirement. And that comes with its own problem.
7. How to Share a House All Day Without Straining Your Marriage
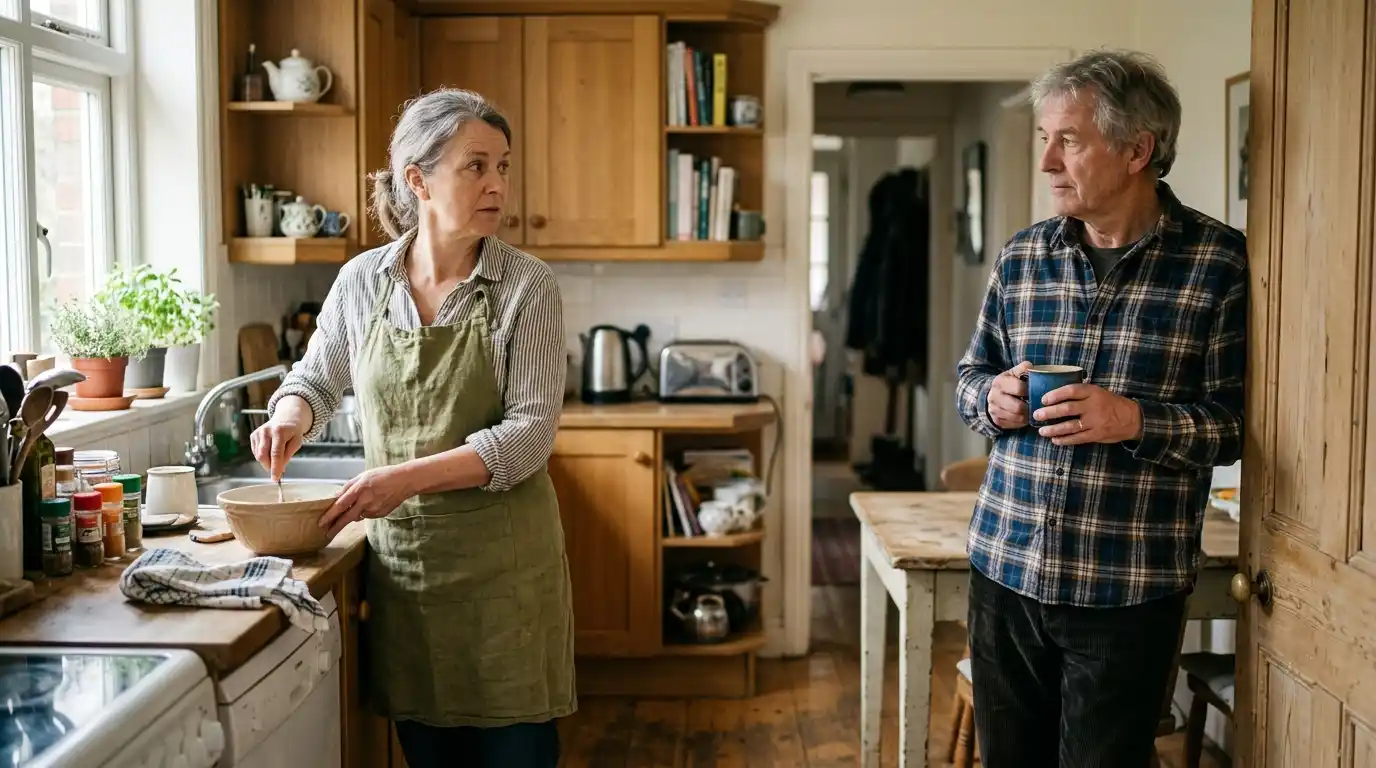
It is nine in the morning. You are both in the kitchen. Neither of you expected the other to be there.
You retired. She did not retire from her life. She has a routine, a schedule, friends who come by, and a way of running the day that worked fine for years without you in it.
Now you are in it. All day. Every day.
This is a bigger risk than most men think. Divorce after 50 has climbed steadily even as divorce overall has fallen. Somewhere around a third to four in ten of all divorces now involve someone over 50.
Among people over 65 the rate has roughly tripled in a generation. Second marriages carry meaningfully higher risk than first ones, which matters for the many men reading this on their second.
The financial damage is real for both people, and it lands at the worst possible time. Men see their standard of living drop by roughly a fifth after a late divorce, and unlike women, men’s decline tends to stick rather than recover.
The cause is rarely a dramatic falling out. It is usually two people who never talked about what the days would look like.
What to do this week: have the conversation before the date, not after. Treat it as logistics, which is a conversation most men will actually sit through. Four questions cover most of it:
- Who has the house during the day, and when?
- What does each of you do alone, and is that protected?
- What do the two of you do together that neither of you did before?
- How much of the housework shifts, and to whom?
That last one causes more arguments than money does. If she has run the house for thirty years and you now have forty spare hours a week, the split has to change. Say so out loud before she has to ask.
Two things are left. They are the two men are least likely to raise with anyone.
8. How to Protect Your Body and Your Mood
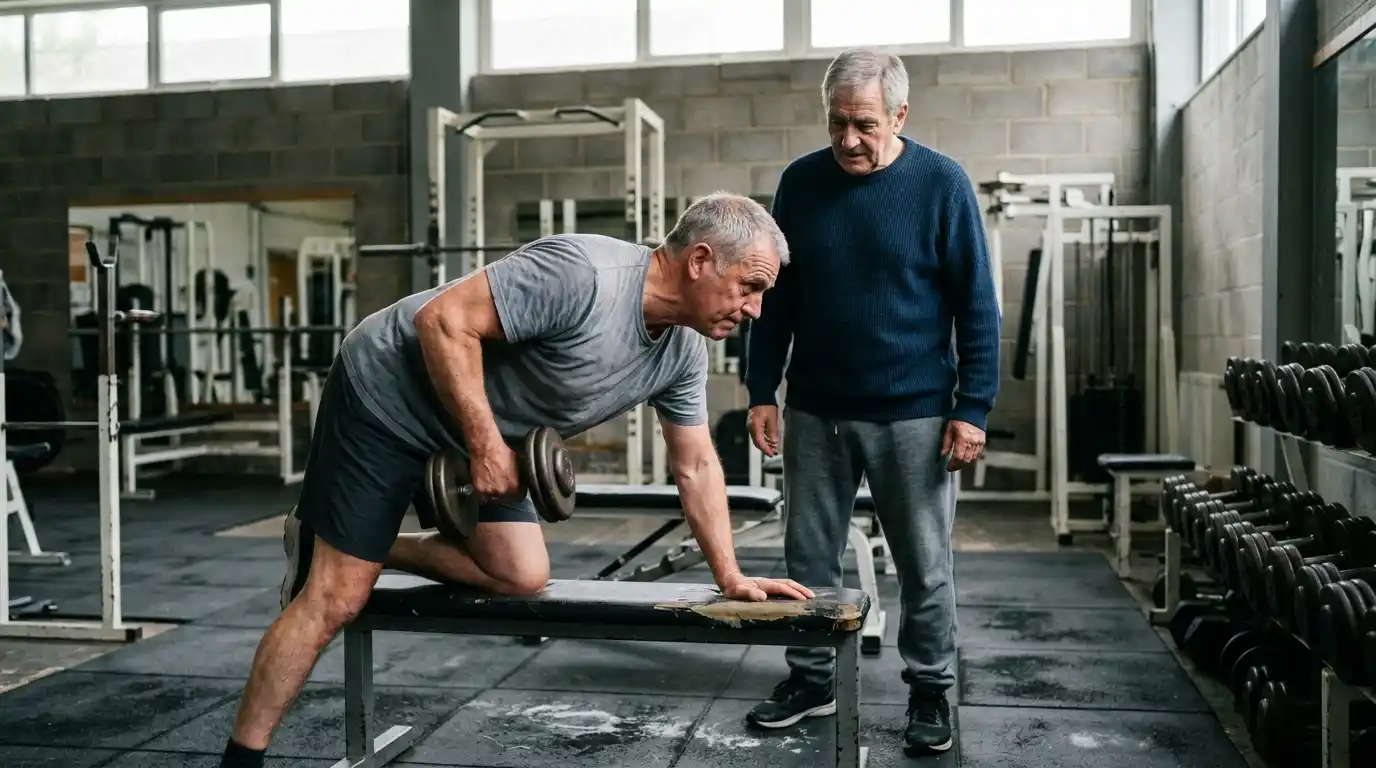
Walking the dog is not a training program. Neither is yard work, or eighteen holes in a cart.
Those things are good. They are just not the thing that keeps you independent at 80.
Strength is. After 60 you lose muscle faster than you lose motivation, and muscle is what lets you carry groceries, climb stairs, get up off the floor, and survive a fall without it changing your life. Only about a third of adults over 45 do any strength work twice a week. It is the half of the advice men skip, and it is the half that matters most later.
The standard guidance is 150 minutes of moderate movement a week plus two strength sessions. Lifting also helps your thinking, not just your body. Resistance training improves focus and problem solving in older adults, which ties this straight back to the purpose section above.
Retirees’ own ratings of their physical health have been slipping in recent surveys, not improving. Free time alone does not make men healthier.
What to do this week: put two strength sessions in the calendar as appointments, the same way you would a doctor visit. Do it with another man if you can, so it solves the friendship problem at the same time. Two markers are worth tracking: your grip strength, and whether you can get off the floor without using your hands.
The one men do not talk about
This is the part that gets left out of most articles like this, so here it is plainly.
Among men, the risk of suicide is highest not in the teenage years or midlife, but after 75. The rate in that group is the highest of any age and sex group in the country, several times higher than for women the same age.
Researchers point to the same pressures this article has been describing: the loss of a work role, divorce, money worry, illness, and a strong habit of not asking for help.
Retirees’ ratings of their own emotional wellbeing have been falling too.
A low mood that hangs around for more than two weeks is not a personality trait and it is not an adjustment period. It is a symptom, and it responds to treatment the way a bad knee does. You would not walk on a broken leg for a year to see if it sorted itself out.
What to do this week: if you have felt flat, irritable, or uninterested for more than two weeks, tell your primary care doctor at your next visit. Say it in plain words. Ask about it the same way you would ask about chest pain. That one sentence is the whole fix, and most men never say it.
Most men leave every day open and hope a structure turns up on its own. Set these four first, then leave the rest genuinely free.
Pick the single section where you recognised yourself, and do one fix this week. One decision made on purpose beats another year of reading about it.
Frequently Asked Questions
How long does it take to adjust to retirement?
For most men, the first few weeks feel great and the trouble starts somewhere between month two and month six, once the backlog of projects runs out. Men who set up a weekly structure before their last day tend to move through it faster. Men who wait until they feel bad before doing anything about it tend to take a year or more.
Is it better to retire at 62 or wait until 65 or later?
The money answer usually favors waiting, because your Social Security check grows for every year you delay up to 70 and your savings get fewer years to cover. But the right answer depends on your health, your job, and whether your wife will rely on your survivor benefit. Run your own numbers rather than following a rule.
How much money do I need to retire comfortably?
There is no single figure, and anyone who gives you one without asking about your expenses is guessing. A better approach is to work backward. Add up what you actually spend in a year, subtract your Social Security and any pension, and see what is left for your savings to cover. Then check whether that gap sits within a sustainable withdrawal rate.
What should I do in the first year of retirement?
Build the week before you fill it. Pick two fixed commitments that involve other people, two strength sessions, and one thing you are learning. Then leave the rest open. Most men do the opposite: they leave everything open and hope structure appears on its own.
Is it normal to feel down after retiring?
A few weeks of feeling adrift is common and usually passes as you build new routines. Feeling flat, irritable, or uninterested for more than two weeks is different, and it is worth raising with your doctor. It is treatable, and getting help early is the difference between a rough few months and a rough few years.

